Categories
Bay Area California, Bay Area Real Estate, loansPublished September 21, 2026
Jumbo Loans Explained: What Bay Area Buyers Need to Know
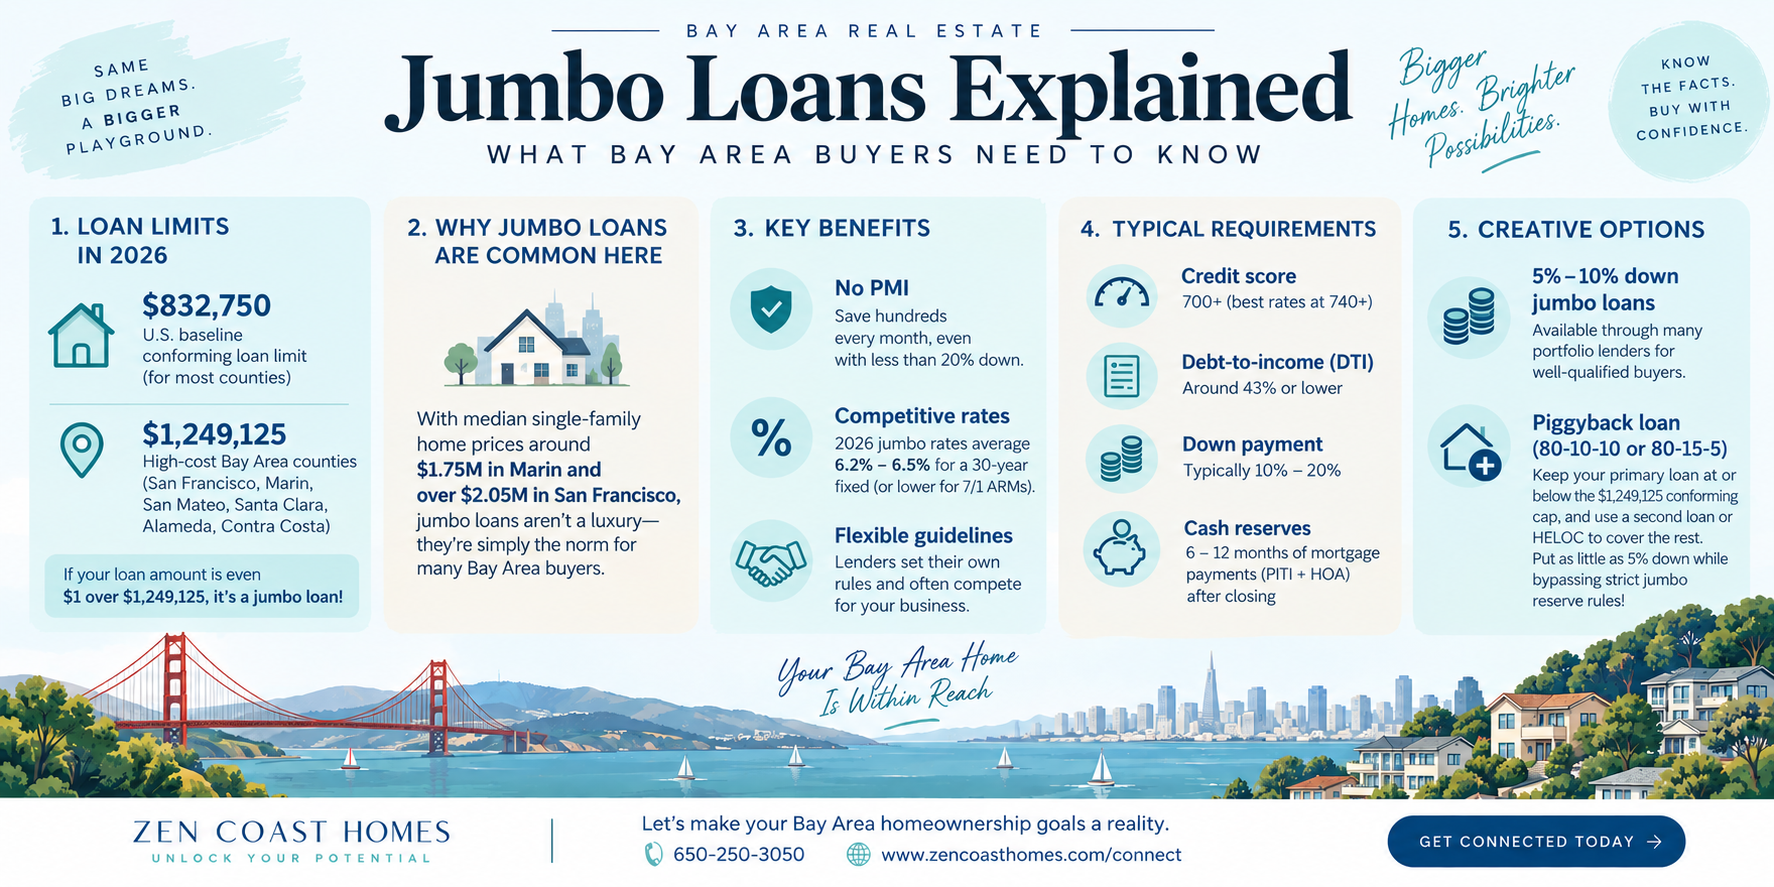
Finding your dream home in San Francisco or Marin County is thrilling, but looking at Bay Area price tags can give anyone a quick case of sticker shock! When your mortgage balance climbs above standard government limits, you officially cross into jumbo loan territory. Every year, the Federal Housing Finance Agency (FHFA) sets the baseline conforming loan limit across the U.S.—which sits at $832,750 for 2026. However, because living by the Bay comes with premium real estate, high-cost counties like San Francisco, Marin, San Mateo, Santa Clara, Alameda, and Contra Costa get an elevated conforming ceiling of $1,249,125 for a single-family home. If your mortgage is even one dollar over $1,249,125, you are getting a jumbo loan!
In cities where median single-family home prices hover around $1.75 million in Marin and exceed $2.05 million in San Francisco, needing a jumbo loan isn't a rare luxury status symbol—it’s just standard operating procedure for everyday buyers. Unlike conforming loans that get bought and backed by government-sponsored entities like Fannie Mae and Freddie Mac, jumbo mortgages are held directly by lenders in their own portfolios. This means banks write their own rulebooks, setting flexible guidelines and competing hard for your business.
Here’s the plot twist that surprises most first-time Bay Area home shoppers: jumbo loans come with some incredible perks! For starters, jumbo loans completely eliminate Private Mortgage Insurance (PMI)—saving you hundreds of dollars every month, even if you put down less than 20%. On top of that, 2026 jumbo interest rates (averaging around 6.2% to 6.5% for a 30-year fixed, or lower for 7/1 ARMs) are remarkably close to standard conforming rates. Because banks love building long-term relationships with high-earning Bay Area professionals, they often price jumbo loans very aggressively.
So, what does it take to snag one of these loans? Jumbo underwriters want to know you're financially solid, which means clearing a few VIP hurdles. Expect lenders to look for a credit score of 700 or higher (with the sweetest rate discounts kicking in at 740+), a debt-to-income (DTI) ratio capped around 43%, and a down payment between 10% and 20%. You'll also need post-closing cash reserves—meaning 6 to 12 months of mortgage payments (covering principal, interest, taxes, insurance, and HOA fees) sitting comfortably in your liquid or investment accounts after closing.
Don't have a giant mountain of cash ready for a 20% down payment and 12 months of reserves? Don't stress—there are clever financing workarounds! Many portfolio lenders offer 5% to 10% down jumbo options for buyers with top-tier credit. Alternatively, you can use a piggyback loan structure (like an 80-10-10 or 80-15-5), where your primary mortgage stays right at or below the $1,249,125 conforming cap to get standard conforming approval, while a second loan or HELOC covers the rest—allowing you to put as little as 5% down while bypassing strict jumbo reserve rules!
Navigating the high-stakes San Francisco and Marin real estate market doesn't have to feel intimidating once you understand how jumbo loans work. Getting pre-approved early with a savvy local lender is your best move—and partnering with an experienced local real estate agent makes all the difference when crafting winning offers in competitive Bay Area neighborhoods. Ready to turn your Bay Area homeownership goals into reality? Reach out to our team today ay 650-250-3050 or www.zencoasthomes.com/connect to get connected with trusted local mortgage specialists, explore current market opportunities, and take the first step toward opening the front door to your dream home!
Jennie Lok
Real Estate Agent and Passive Income Coach | Zen Coast Homes | Real Brokerage Technologies
or another way